Most people planning a new home can tell you their target price down to the dollar. Fewer can tell you what their homeowners policy will cost, how many months of rent they’ll pay while the house goes up, or what happens if interest rates jump halfway through. That’s not a knock on anyone. Those numbers just don’t show up on a floor plan.
If you’re setting a budget for building a house in Southeast Missouri this year, this is the list we’d want you to see before you sign anything. It covers the three places 2026 buyers get caught off guard most often: insurance premiums, financing timelines, and what construction actually costs right now.
Table of Contents
Why your budget for building a house needs a fresh look in 2026
A lot of the budgets we see were built on numbers from a year or two ago. Some of those numbers have moved.
Mortgage rates are one of them. Freddie Mac’s weekly survey put the 30-year fixed at 6.95% on September 17, 2026, up from 6.76% the week before and 6.26% a year earlier. The Federal Reserve also raised its benchmark rate on September 16, its first increase in three years.
Building materials are another. In August 2026, the price index for inputs to new residential construction was up 7.8% from a year earlier, according to NAHB’s read of federal producer price data.
None of this means you should put your plans on hold. It means a budget you made in 2024 probably needs an update before you commit to it.
1. Insurance: the cost that shows up after move-in
Insurance is easy to forget because you don’t pay it until the house is finished. Then it’s part of your monthly payment for as long as you own the home.
Homeowners premiums in Missouri
U.S. News puts the average Missouri homeowners policy at $3,036 a year, based on $300,000 in dwelling coverage. Other trackers land anywhere from about $2,800 to $3,500, so treat any single average as a starting point rather than a quote. A custom home with more dwelling coverage will usually cost more to insure than that sample house.
Two things to ask your agent about early:
- Your wind and hail deductible. Many Missouri policies now use a percentage-based deductible instead of a flat dollar amount. On a home insured for $500,000, a 2% deductible means you’d cover the first $10,000 of a storm claim yourself.
- What renewals look like. Nationally, homeowners renewing their policies saw an average increase of 10.6% in the first half of 2026, per Matic’s 2026 home insurance report. That’s slower than the two years before, but it’s still worth planning for.
Get real quotes while you’re still in design. It costs nothing, and it turns a guess into a line item.
Earthquake coverage is its own line item here
This one is specific to our corner of the state. A standard homeowners policy doesn’t cover earthquake damage. It has to be added as an endorsement or bought as a separate policy. The Missouri Department of Commerce and Insurance reports that only 10.4% of residences in Missouri’s New Madrid region had earthquake coverage in 2024, down from 18.3% in 2015.
Price depends heavily on where you are. State data reported by Insurance Business showed a $200,000 home in Caruthersville averaging about $2,134 a year for earthquake coverage, compared with $398 in St. Louis. Whether you buy it is your call. It just belongs in the conversation, and in the budget, before you close.
Builder’s risk while the home is under construction
While your home is being built, it needs protection against things like fire, storm damage, or materials walking off the site. That’s builder’s risk insurance. Depending on the builder and the loan, it might be carried by the builder, required by your lender, or purchased by you. Get the answer in writing so it isn’t a surprise at your construction loan closing.
2. Financing timelines: what it costs to wait while you build
Building takes time. A typical custom build in the Cape Girardeau and Jackson area takes about 9 to 12 months, and several costs run on that clock.
Interest on construction draws
With a construction-to-permanent loan, you usually pay interest only on the money that’s been drawn so far. Those payments start small and grow as the house goes up. They’re manageable, but they come before your first regular mortgage payment, so they need a spot in the budget. Some construction-phase rates move with short-term rates, which means a Fed decision can change what you pay mid-build. Ask your lender how yours is set.
Paying for two places at once
Unless you’re staying with family, you’ll be paying rent or a current mortgage the whole time your new home is under construction. Multiply that by the months of the build, then add a cushion for weather. For a lot of families, this ends up being the biggest number they never wrote down.
Rate locks and appraisals
Ask when your permanent rate gets locked, how long the lock lasts, and what an extension costs if a delay pushes your finish date. Also ask what happens if the appraisal comes in under the contract price. In most cases, the difference comes out of your pocket.
Property taxes and escrow
Your monthly payment will usually include property taxes and insurance through escrow. Missouri assesses residential property at 19% of market value, and your new home will be taxed on the finished house, not the empty lot you may have been paying on. Your county assessor’s office can help you estimate the figure.
Want to see how taxes and insurance change your monthly number? Our free Affordability Calculator lets you run it with your own figures in about a minute.
3. Real construction costs in Southeast Missouri right now
The construction itself is now the largest share of what a new home costs. NAHB’s most recent Cost of Constructing a Home survey found construction made up 64.4% of the average new-home sales price in 2024, a record for the series. Interior finishes were the biggest piece, at 24.1% of construction costs.
Prices have kept climbing since. In August 2026, building materials (not counting energy) were up 5.1% from a year earlier, and diesel fuel was up 77.7%. Diesel touches every delivery truck and piece of equipment on a jobsite.
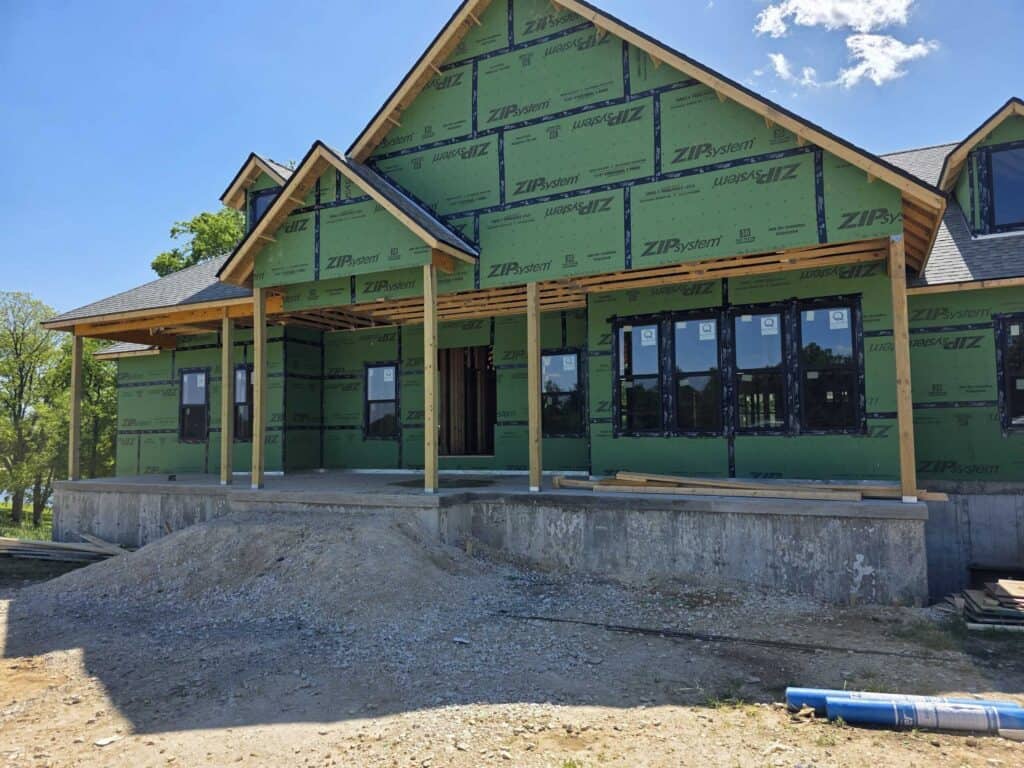
Here’s where those costs tend to show up in a Southeast Missouri budget:
- Allowances that don’t match your taste. If your budget assumes one countertop and you fall for another, the difference is yours. Making selections early is one of the best ways to protect your number.
- Site work. Grading, driveways, utility connections, and soil conditions vary a lot from lot to lot around here. If you already own land, here’s what a good builder checks first.
- Lead-time items. Windows, appliances, and some fixtures can take a while to arrive. Ordering late can mean paying more or waiting longer.
- Contingency. We recommend setting aside 5 to 10% of your build budget for the things no one can fully predict.
For more on the numbers, see our guide to the cost per square foot to build a house in Missouri and our earlier post on the hidden costs of building a home, which goes deeper on site prep, permits, and utility hookups.
Your 2026 budget checklist
Before you finalize a budget for building a house, make sure each of these has an actual number next to it:
- A homeowners insurance quote, with your wind and hail deductible noted
- An earthquake coverage quote, even if you decide to pass
- Builder’s risk coverage: who carries it and what it costs
- Construction-phase interest, estimated month by month
- Rent or your current mortgage for the full build, plus a cushion
- Rate lock length and extension fees
- Property taxes on the finished home
- Selections priced at what you actually want
- A 5 to 10% contingency
How we keep these numbers out in the open
We build on a budget-based contract. Your real numbers are on the table from the start, and we review your budget with you at each milestone instead of handing you a surprise at the end. We’ll also connect you with trusted local lenders who can build the construction timeline into your plan from day one.
We can’t set your insurance premium or predict the Fed’s next move. What we can do is make sure you’ve asked the right questions before those numbers matter.
Build with the whole picture in front of you
The price of the house is only part of what it costs to own it. Insurance, the months you spend waiting, and today’s material prices all belong in the real number. Plan for them now and they stop being surprises later.
If you want a place to start, download our free Real-Home Planning Guide. It walks you through the build step by step, so you know what’s coming before you commit. Rather talk it through? Call us at 573-722-2402.
Frequently asked questions
What do people most often forget when setting a budget for building a house?
The costs that sit outside the construction contract: homeowners and earthquake insurance, interest during construction, rent or a current mortgage while the home is built, and property taxes on the finished home. Site work and finish upgrades are also common surprises.
How much is homeowners insurance in Missouri in 2026?
Published averages run from about $2,800 to $3,500 a year, and U.S. News cites $3,036 for a policy with $300,000 in dwelling coverage. Your cost depends on your home’s value, location, deductible, and claims history, so get quotes during design.
Does homeowners insurance cover earthquakes in Southeast Missouri?
No. Standard homeowners policies don’t cover earthquake damage. You need a separate endorsement or policy, and the price varies a lot by county.
How much contingency should I include when building a home?
We recommend setting aside 5 to 10% of your build budget for things no one can fully predict. The goal is to finish your home with that cushion still in place.
How long should I budget for rent or my current mortgage during construction?
A typical custom build in the Cape Girardeau and Jackson area takes about 9 to 12 months. Budget for the full span, plus a cushion in case weather or material lead times push back your move-in date.